
What “nesting” means
Nesting is the use of a virtual account to serve customers of the account holder without those customers being onboarded and monitored as Fin customers in their own right. It is a form of hidden financial intermediation, and it is prohibited by Fin’s regulators and banking partners. Nesting is prohibited if you:- collect funds from multiple third parties into a virtual account you hold, and then pay those parties out to different recipients on their behalf; or
- use your virtual account to run any activity typical of a bank, money services business, payment service provider, e-money institution, virtual asset service provider, prepaid provider, or similar business, unless you have disclosed that activity to Fin in advance and received written acceptance.
How Fin works with developers and their customers
Fin is a B2B infrastructure platform. Developers integrate with Fin’s APIs to offer financial services to their own customers. Here is how the relationship works:- Fin onboards the developer. We perform KYB on the developer’s business, review their AML policies, onboarding criteria, and customer risk assessment framework. Once approved, the developer can use Fin’s APIs. At onboarding, the developer also accepts Fin’s Developer No-Nesting Terms.
- Each end customer must be onboarded individually. Fin requires every customer (individual or business) to go through KYC or KYB via Fin’s platform before they can receive a virtual account or transact. There are no exceptions to this. At onboarding, each end customer also accepts Fin’s Customer No-Nesting Terms.
- Virtual accounts are issued per onboarded entity. Once a customer passes verification and meets our banking partner’s eligibility criteria, they receive their own virtual account. The developer themselves also receives a virtual account as part of their onboarding, if eligible.
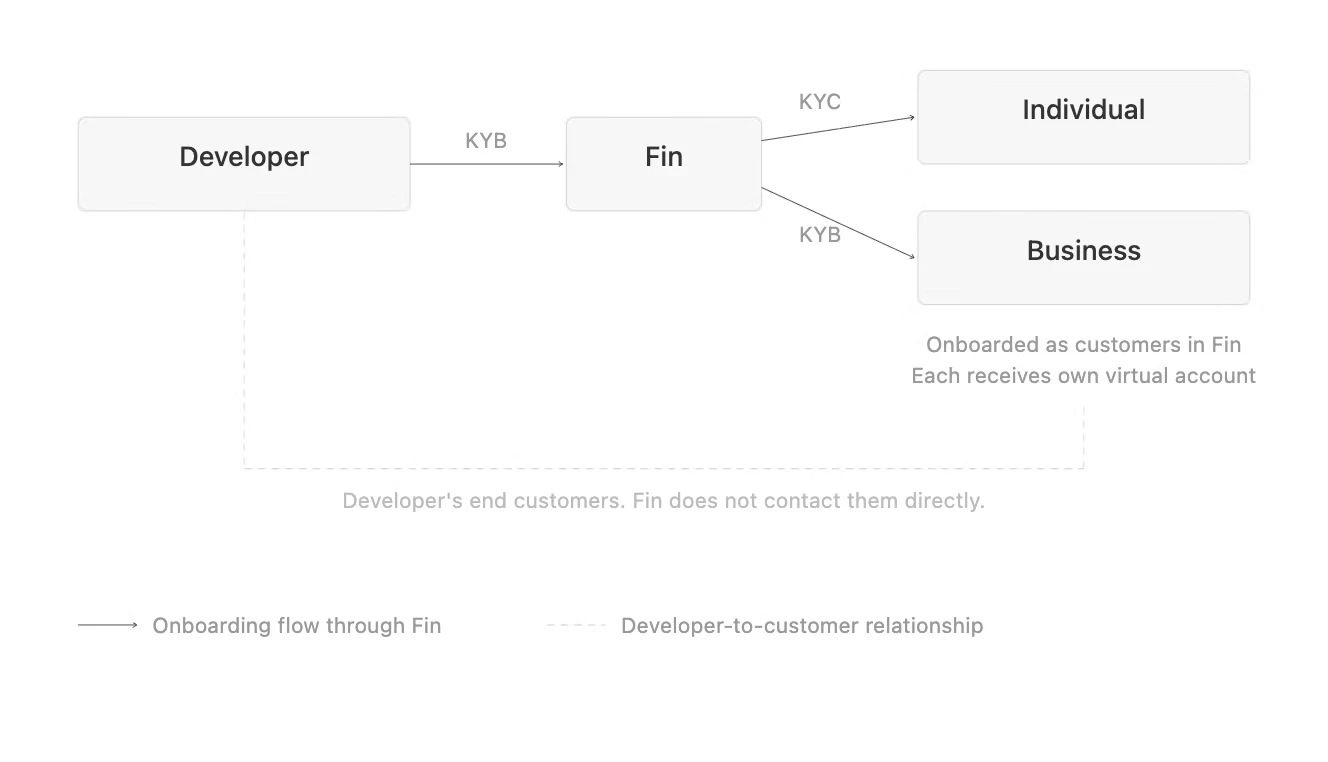
Fin does not contact a developer’s end customers directly. All customer communication is handled by the developer.
Every account holder must be the beneficial owner of funds
Every account holder must be the beneficial owner of the funds in their virtual account. That means the funds must belong to the account holder, even if they are paid in by a named third party such as a customer, supplier, or payment processor. The account holder must also be onboarded with Fin. What Fin does not support is nesting, meaning using a virtual account to receive funds that beneficially belong to someone else who has not been onboarded with Fin. This includes pooling funds from multiple third parties, operating as a money services business, payment service provider, or financial institution through Fin’s infrastructure, or otherwise acting as an intermediary for undisclosed downstream customers.What “beneficial ownership” means in practice
The funds in a virtual account must beneficially belong to the account holder. Where they are paid in by a named third party, the account holder must be able to demonstrate a legitimate business relationship with that third party. Example: Agency or drop-shipping business A drop-shipping store onboarded with Fin receives a payment from a supplier or buyer. This is acceptable if:- The payment is tied to a specific invoice or contract.
- The account holder can provide documentation (invoice, purchase order, contract) linking the payment to their business activity.
- Compliance may request these documents for any inbound transaction that does not originate from the account holder’s own named bank account.
- The business has a verified account with the payment processor under the same legal name as the entity onboarded with Fin.
- Fin will require a letter or document confirming the account relationship between the business and the payment processor.
Documents Fin may request for higher-risk or high-volume activity
For payments that are high in value, high in volume, or that raise compliance questions, Fin will request the following if they were not already provided at onboarding:- Purpose of the payment.
- Proof supporting the purpose (e.g., invoice, contract, or purchase order).
- Source of funds.
- Proof of source of funds.
- For customers based in or transacting to higher-risk jurisdictions, Fin may also request additional recipient and counterparty information.
Restricted business activities
Certain business types and activities cannot be facilitated through Fin. See Restricted and High-Risk Businesses for the full list.Frequently asked questions
Can I receive third-party funds in my virtual account?
Can I receive third-party funds in my virtual account?
Yes, if the funds beneficially belong to you. Payments from a named third party, such as a payment processor (Stripe, Nuvei, Adyen), a supplier, or a customer of yours, are permitted where you can demonstrate a legitimate business relationship and the funds are yours. What is not permitted is receiving funds that beneficially belong to another person, for example by pooling money from multiple people who have not themselves been onboarded with Fin.
Do I need to onboard each of my customers with Fin?
Do I need to onboard each of my customers with Fin?
Yes. Fin requires KYC (for individuals) or KYB (for businesses) on every customer before they can receive a virtual account or transact. You cannot use your own virtual account to receive funds on behalf of your customers.
Can I use one virtual account to collect payments from all my customers?
Can I use one virtual account to collect payments from all my customers?
No. This is a nested flow and is not supported. Each customer must be onboarded separately and issued their own virtual account. Using a single account to pool third-party funds would classify the activity as operating a money service business, which Fin cannot facilitate.
I receive payments from Stripe/Nuvei/Adyen into my account. Is that allowed?
I receive payments from Stripe/Nuvei/Adyen into my account. Is that allowed?
Yes, as long as you have a verified account with the payment processor under the same legal name as your Fin account, and you can provide a letter or document confirming the relationship. Because the funds beneficially belong to you, this is permitted.
What happens if I receive a payment from someone who is not the account holder?
What happens if I receive a payment from someone who is not the account holder?
Fin’s compliance team may flag the transaction and request supporting documentation such as an invoice, contract, or proof of business relationship. If the payment cannot be verified as legitimate first-party activity, it may be returned or the account may be restricted.
I'm a developer. Do I also get a virtual account?
I'm a developer. Do I also get a virtual account?
Yes. As part of the developer onboarding process (KYB), if your entity meets the eligibility criteria of our banking partners, you will receive a virtual account automatically.
What documents do I need for large or frequent payments?
What documents do I need for large or frequent payments?
Fin may request: (1) purpose of payment, (2) proof of purpose (invoice, contract), (3) source of funds, (4) proof of source of funds. In high-risk jurisdictions, recipient information may also be required. These are standard compliance requirements and apply to all high-volume activity.
Can I operate as a payment processor or financial institution using Fin?
Can I operate as a payment processor or financial institution using Fin?
Not by default. Fin does not support developers using virtual accounts to run money service businesses, payment processing operations, or other financial institution activities without prior disclosure and written acceptance. If your business model does involve licensed intermediation, you must disclose this at onboarding. Fin will assess it separately and either accept, condition, or decline the relationship. See the restricted business activities page for the full list of activities Fin will not support.
What are the No-Nesting Terms and when do I accept them?
What are the No-Nesting Terms and when do I accept them?
At Virtual Account onboarding, every developer accepts Fin’s Developer No-Nesting Terms and every end customer accepts Fin’s Customer No-Nesting Terms. These set out your commitment not to use a virtual account for nested activity, and Fin’s rights if you do. Acceptance is a condition of Virtual Account issuance and continued availability. You can request a copy of the version you accepted at any time.